Trends
The biggest AI industry trends for 2027 are a capex supercycle that is already contracted into 2027, electricity becoming the real limit on growth, and enterprise adoption that keeps spreading while profit impact stays flat. Here are all ten, with the number behind each:
Every figure comes from the organization that measured it (SEC filings, the IEA, EIA, McKinsey, Stanford's AI Index, EUR-Lex and state legislatures), plus our own search data where it adds something.
Let's get into it.
The scale of AI infrastructure spending is now visible in every big tech filing. The IEA's Key Questions on Energy and AI report says capital spending by five large tech companies exceeded $400 billion in 2025 and is expected to rise another 75% in 2026, more than global investment in oil and gas production.
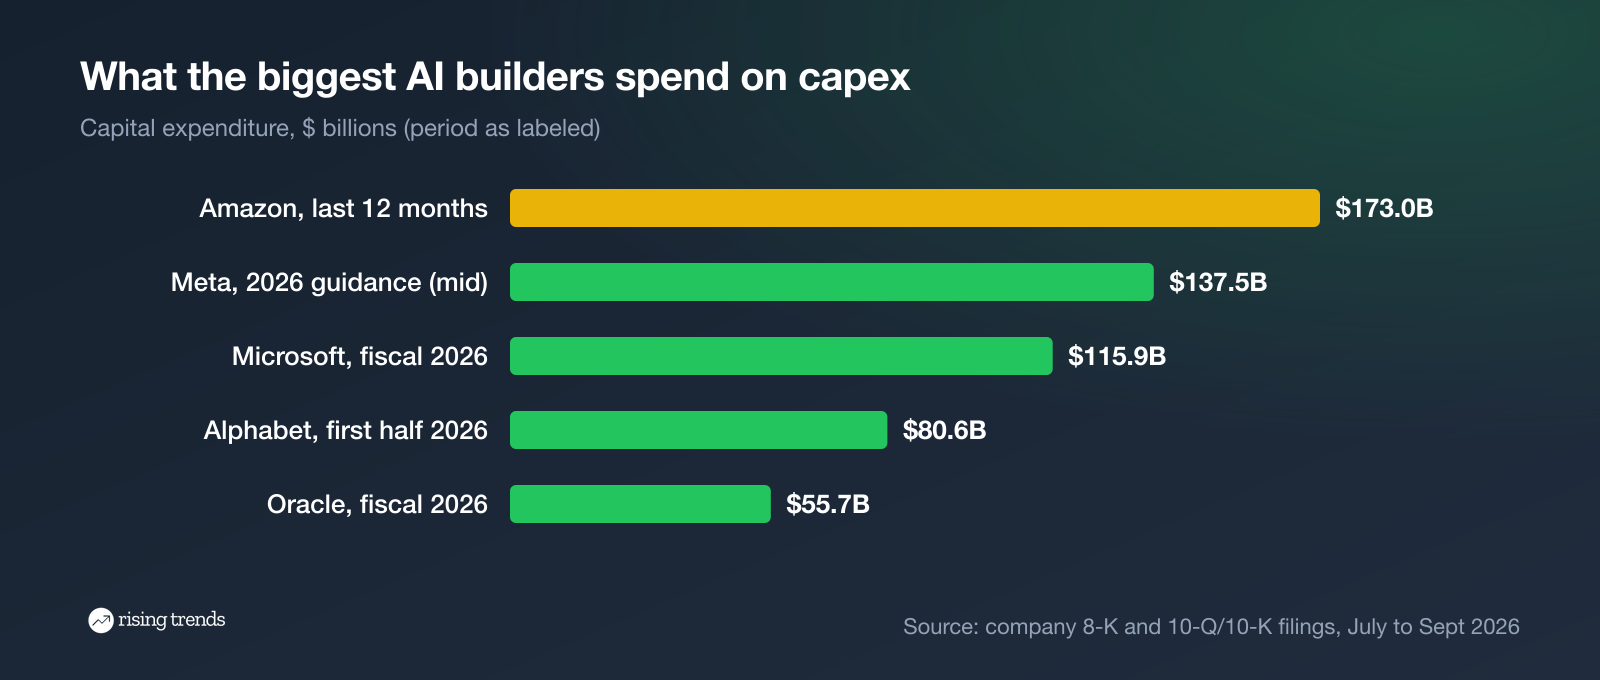
The filings show where that money goes. Amazon spent $173.0 billion on property and equipment over the last 12 months, pushing trailing free cash flow negative, and said the increase "primarily reflects investments in artificial intelligence." Microsoft spent $115.9 billion in fiscal 2026, up from $64.6 billion. Meta guided $130 to $145 billion of capex for 2026, and its Q2 free cash flow shrank to $784 million.
On the supply side, Nvidia reported data center revenue of $89.0 billion in one quarter, up 117%, and guided to $108 billion of total revenue for the next.
Alphabet raised $49.6 billion of new equity in June 2026, including a $10 billion placement with a Berkshire Hathaway affiliate, to fund AI infrastructure. It spent $80.6 billion on capex in the first half alone.
Oracle spent $28.5 billion on capex in a single quarter, more than three times a year earlier, sold $20 billion of stock to help pay for it, and reported $664 billion of contracted backlog.
Meta signed about $68 billion of new data center leases in July 2026 that commence in 2027 and 2028, and has $81.65 billion of non-cancelable commitments due in 2027.
No company has put formal 2027 capex guidance in a filing, but the contracts say it anyway. Microsoft's 10-K lists $329.1 billion of datacenter leases signed but not yet started, beginning in fiscal 2027. Meta's 2027 commitments are larger than what it has left to pay in all of 2026.
For buyers, that means more capacity is coming, but the bill for it sits on the balance sheets of the vendors you depend on. When Alphabet and Oracle are issuing stock to fund data centers, pricing discipline and the financial health of your cloud and AI suppliers become part of vendor risk.
The limit on AI growth in 2027 is increasingly the grid.
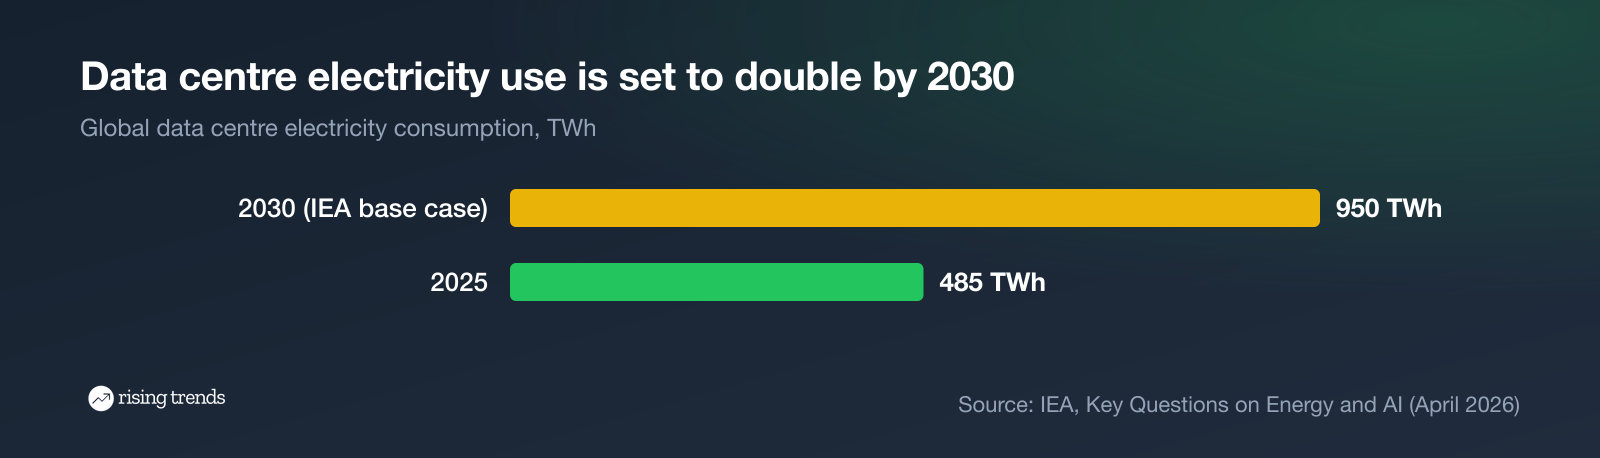
The same IEA report projects data centre electricity use rising from 485 TWh in 2025 to 950 TWh in 2030, with AI-focused data centres set to triple their use. In 2025 alone, data centre electricity demand grew 17%, against 3% for global power demand. The IEA also expects the high-bandwidth memory shortage to last through at least the end of 2027.
In the US, the constraint is already changing policy. According to the EIA's August 2026 Short-Term Energy Outlook, Texas paused new data center development on August 3, 2026 to collect more information on projects under review, and the EIA cut its 2027 Texas load growth forecast from 14% to 6%. Nationally, the EIA expects US electricity use to grow 3% in 2027, driven by large computing centers.
Meta signed nuclear agreements for up to 6.6 GW with Vistra, TerraPower and Oklo, including 20-year deals for more than 2.1 GW from existing plants and new reactors as early as 2030. (We looked at another bet on nuclear for compute in our piece on Radiant Industries.)
Oracle delivered 850 MW of new data center capacity in a single quarter. Anthropic and OpenAI have both made what Amazon calls "multi-year, multi-gigawatt commitments" to its Trainium chips. Compute deals are now sized in gigawatts, not GPUs.
The IEA expects AI server power density to quadruple by 2027 and gas turbine orders rose 70% in 2025. Our inference: more state-level pauses and connection queues after Texas, and more AI capacity sited where power is available rather than where customers are.
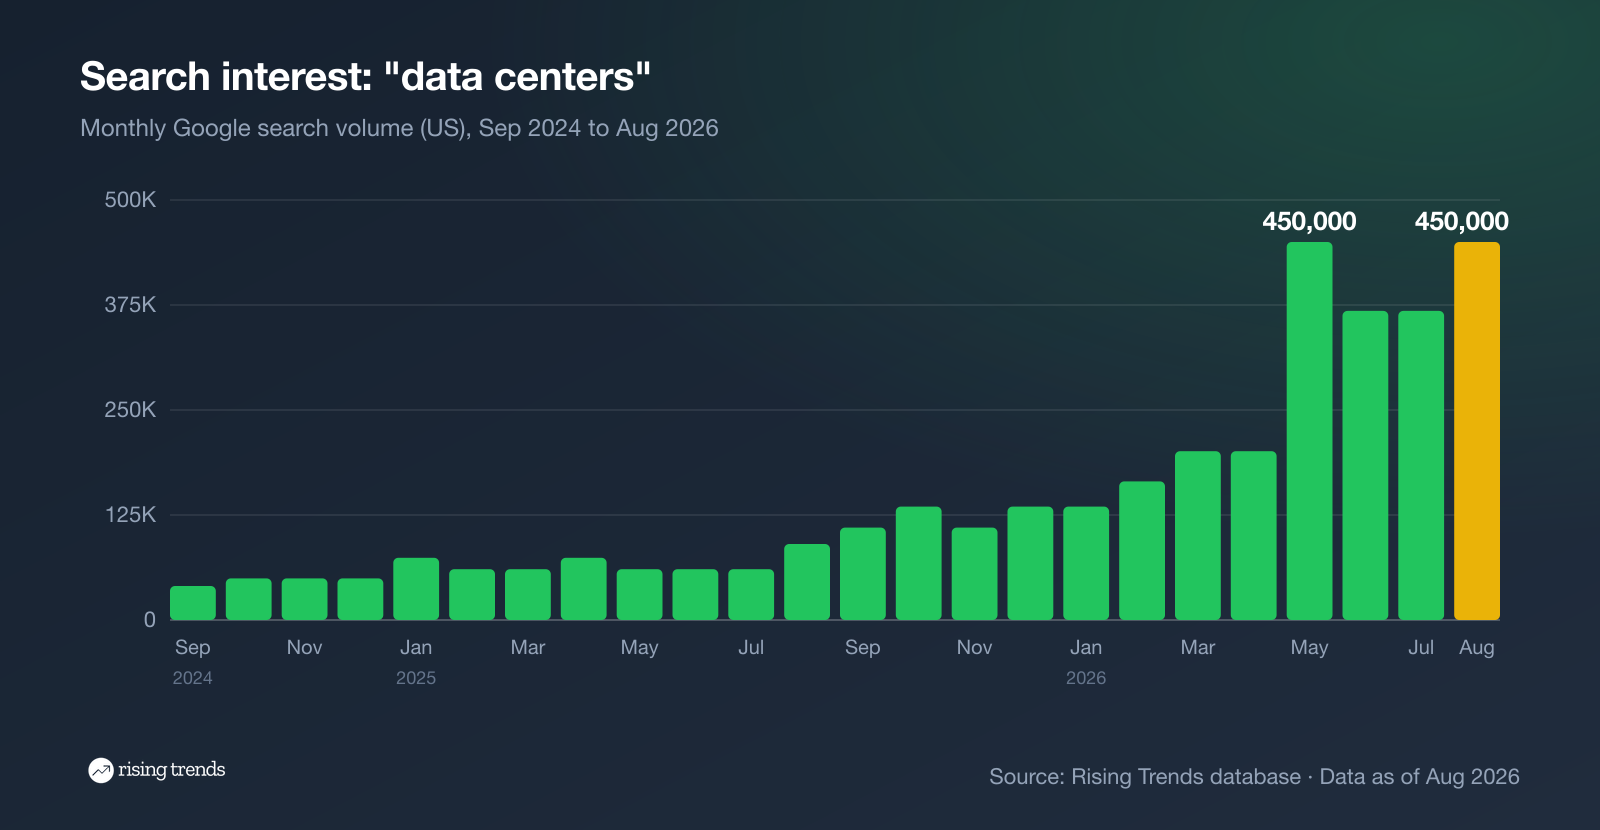
Our search data shows the public noticing. US searches for "data centers" rose 397% in a year, from 90,500 to 450,000 a month (August 2026), and "texas data centers" is up 1,029%.
This is the core tension for anyone who owns an AI budget in 2027.
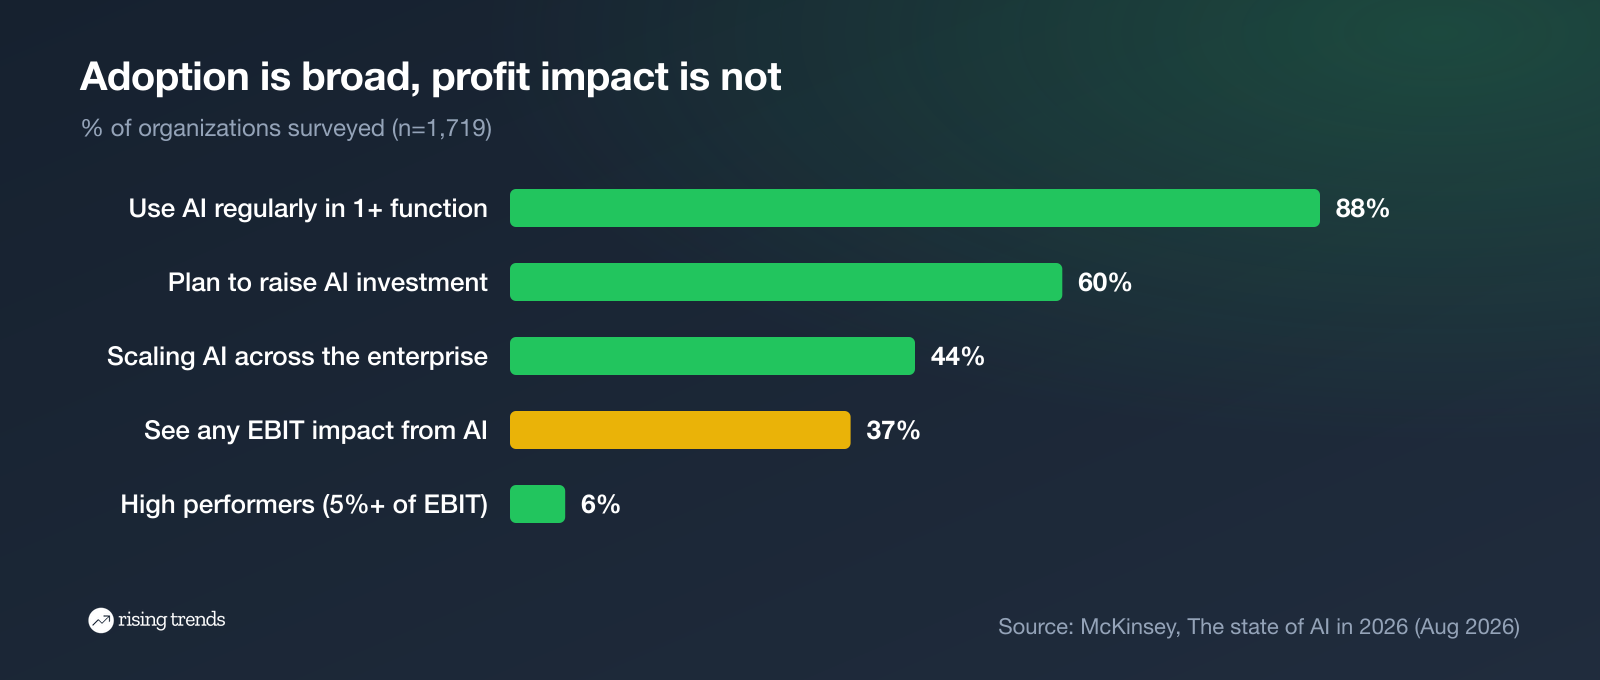
McKinsey's State of AI in 2026 survey (n=1,719, fielded May to June 2026) found nearly 9 in 10 organizations use AI regularly in at least one function, and 44% say AI is now scaling across the enterprise, up from 38%. But only 37% attribute any EBIT impact to AI, essentially unchanged from 2025. The "high performers" getting 5% or more of EBIT from AI stayed at about 6%.
How widespread adoption looks depends on who you ask. The US Census Bureau found 19.8% of US businesses used AI as of May 2026, rising to 37% among firms with 250 or more employees. A Federal Reserve note puts it in perspective: about 18% of firms adopted AI, but 78% of the labor force works at an adopting firm and 41% of workers use generative AI on the job.
Microsoft passed 30 million paid Microsoft 365 Copilot seats. Google says Gemini Enterprise is used by nearly 90% of the Fortune 100. ServiceNow said its AI products crossed $1 billion in annual contract value.
The McKinsey data shows what separates the 6%: nearly three quarters of high performers redesigned their workflows, against one quarter of everyone else.
60% of organizations plan to raise AI investment next year, per McKinsey, so spend keeps rising. The question for 2027 is whether the 37% moves. Expect CFOs to demand outcome metrics, more spend routed through incumbent software vendors, and pilots that cannot show P&L impact getting cut.
AI agents went from demos to deployments in 2026, mostly at large companies.
McKinsey found 40% of large organizations (over $1 billion revenue) report scaling AI agents, up from 27% a year earlier, while smaller firms stayed flat at 22%. On benchmarks, the AI Index reports agent task success on OSWorld rose from about 12% to 66.3%, within 6 points of humans, though agents still fail roughly one in three attempts.
Salesforce reported Agentforce annual recurring revenue above $1.5 billion, up more than 240%, and now bills by "agentic work units" (3.2 billion in Q2, up 97% in a quarter).
ServiceNow said agentic deployments of its AI grew ninefold in nine months.
OpenAI launched its Frontier enterprise agent platform with customers including Oracle, State Farm and Uber, and said Codex had 3 million weekly users.
Gartner has predicted that over 40% of agentic AI projects will be canceled by the end of 2027 because of cost, unclear value or weak risk controls. Put that next to the McKinsey split and the 2027 picture is consolidation: agents running on platform vendors' agent layers (Salesforce, ServiceNow, the hyperscalers), usage-based pricing replacing seats, and governance deciding who keeps their projects.
Our search data shows the same shift from hype to buying. "Agentic ai" searches are down 45% in a year, while "enterprise ai agents" went from 170 to 22,200 a month and "ai agent builders" is up 1,594%. For the deeper agent picture, see our AI agent trends.
The money in AI models is flowing to a very small number of companies.
Anthropic said in May 2026 that its run-rate revenue crossed $47 billion as it raised $65 billion. OpenAI said in March that it was generating $2 billion in revenue per month, with enterprise above 40% of revenue and on track to match consumer by the end of 2026. Both figures are the companies' own run-rates, not audited annual revenue.
The clouds capture the rest. Amazon says its AWS AI business and its chips business each run above $25 billion a year, growing triple digits. Google says its Gemini app has 950 million monthly users and its APIs process 22 billion tokens a minute, up from 16 billion a quarter earlier.
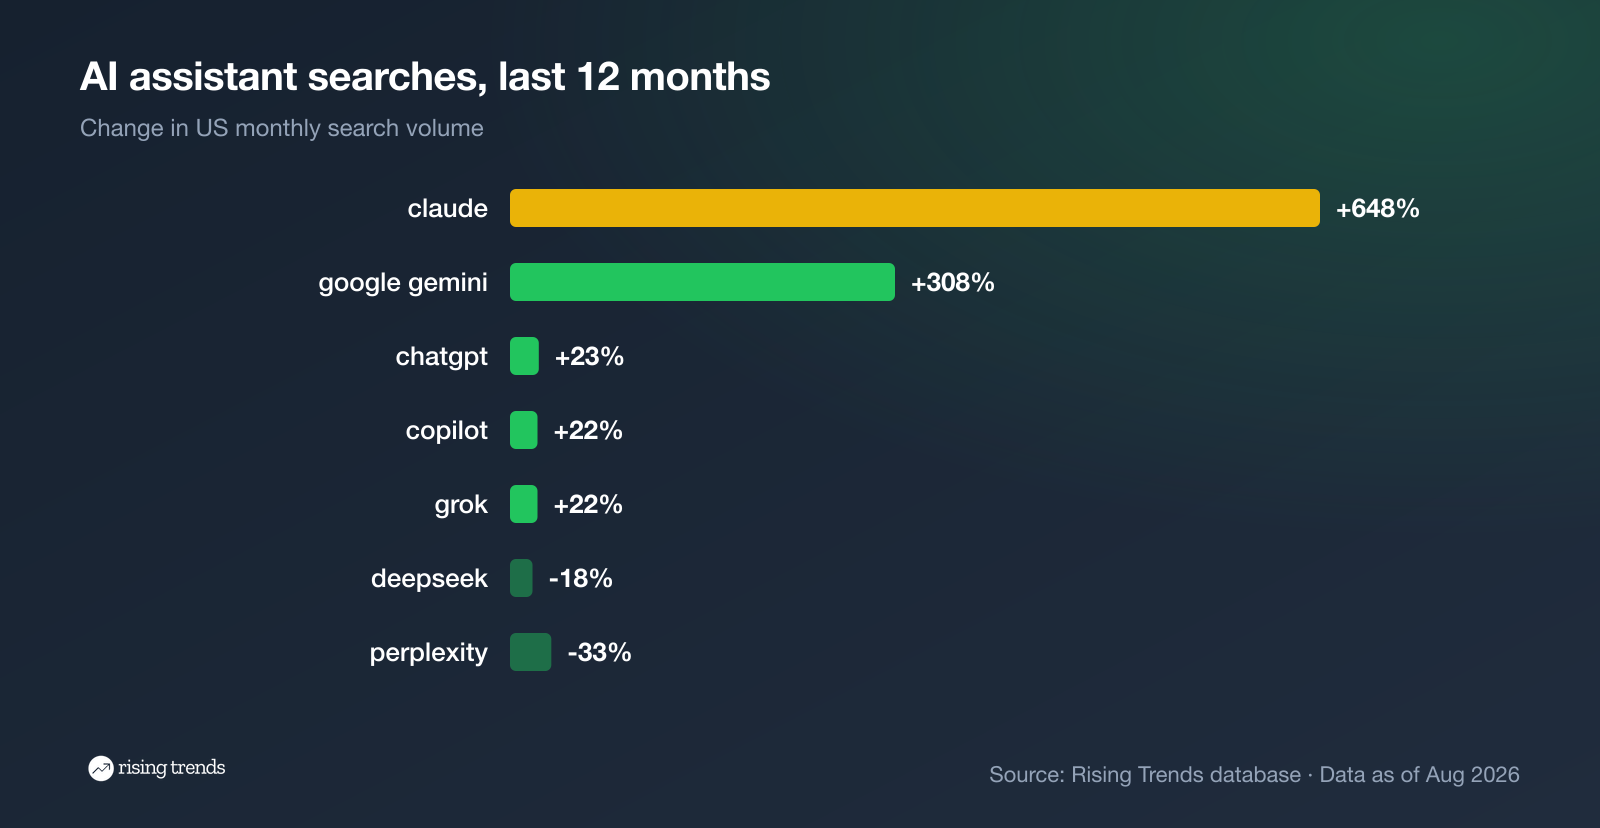
Our search data shows how quickly share is moving inside that small group. US searches for "claude" grew 648% in a year (from 1 million to 7.48 million a month), "google gemini" grew 308% and "chatgpt" grew 23% from a much larger base of 124 million. "Perplexity" fell 33% and "deepseek" 18%.
Concentration is a vendor risk. Both leading labs depend on hyperscaler capital and compute, and switching models is easier than switching clouds. Expect enterprises in 2027 to run multiple models through one cloud, negotiate model access as part of cloud commitments, and treat any single lab as a dependency to hedge.
The cost of "good enough" AI keeps collapsing. The cost of the best AI is not.
On the cheap end, Anthropic's pricing page lists Claude Haiku 5.5 at $0.10 per million input tokens and $0.50 per million output tokens, down from $1 and $5 for the previous Haiku. DeepSeek lists its open-weight V4-Flash at $0.30 and $1.20 at peak hours, half that off-peak. OpenAI said at DevDay that GPT-6.1 Sol delivers near-frontier intelligence at a fifth of the price of its standard model.
On the premium end, prices are rising. Google's Gemini API pricing page shows introductory prices for Gemini 4 Argon doubling on December 1, 2026, and Gemini 3.8 and 3.6 Flash doubling on January 1, 2027. Anthropic has added a new top tier at $10 and $50 per million tokens.
The long-run trend is still down: the AI Index found the cost to run a GPT-3.5-level system fell over 280-fold between late 2022 and late 2024. But total bills rise anyway, because usage grows faster than prices fall. About 20% of organizations told McKinsey that AI operating costs, including tokens, now constrain their use.
OpenAI shows the discipline side. It shut down the Sora app in April 2026 and the Sora API in September, redirecting credits to Codex. Expensive consumer generation that does not pay its way is getting cut, even at the biggest labs.
Expect "token FinOps" to become a real job: routing simple work to cheap models, reserving frontier models for tasks that need them, and budgeting for price increases on tiers that started with introductory pricing. With memory supply tight through 2027, compute prices have less room to fall than the history suggests.
Compliance roadmaps changed in 2026, and most of the new dates land in 2027.
In the EU, Regulation (EU) 2026/1744, the AI "Digital Omnibus," entered into force on July 27, 2026. It moved the AI Act's high-risk obligations from August 2026 to December 2, 2027 for Annex III systems (employment, education, credit and similar uses) and to August 2, 2028 for AI embedded in regulated products. New bans on AI-generated intimate imagery and child abuse material apply from December 2, 2026.
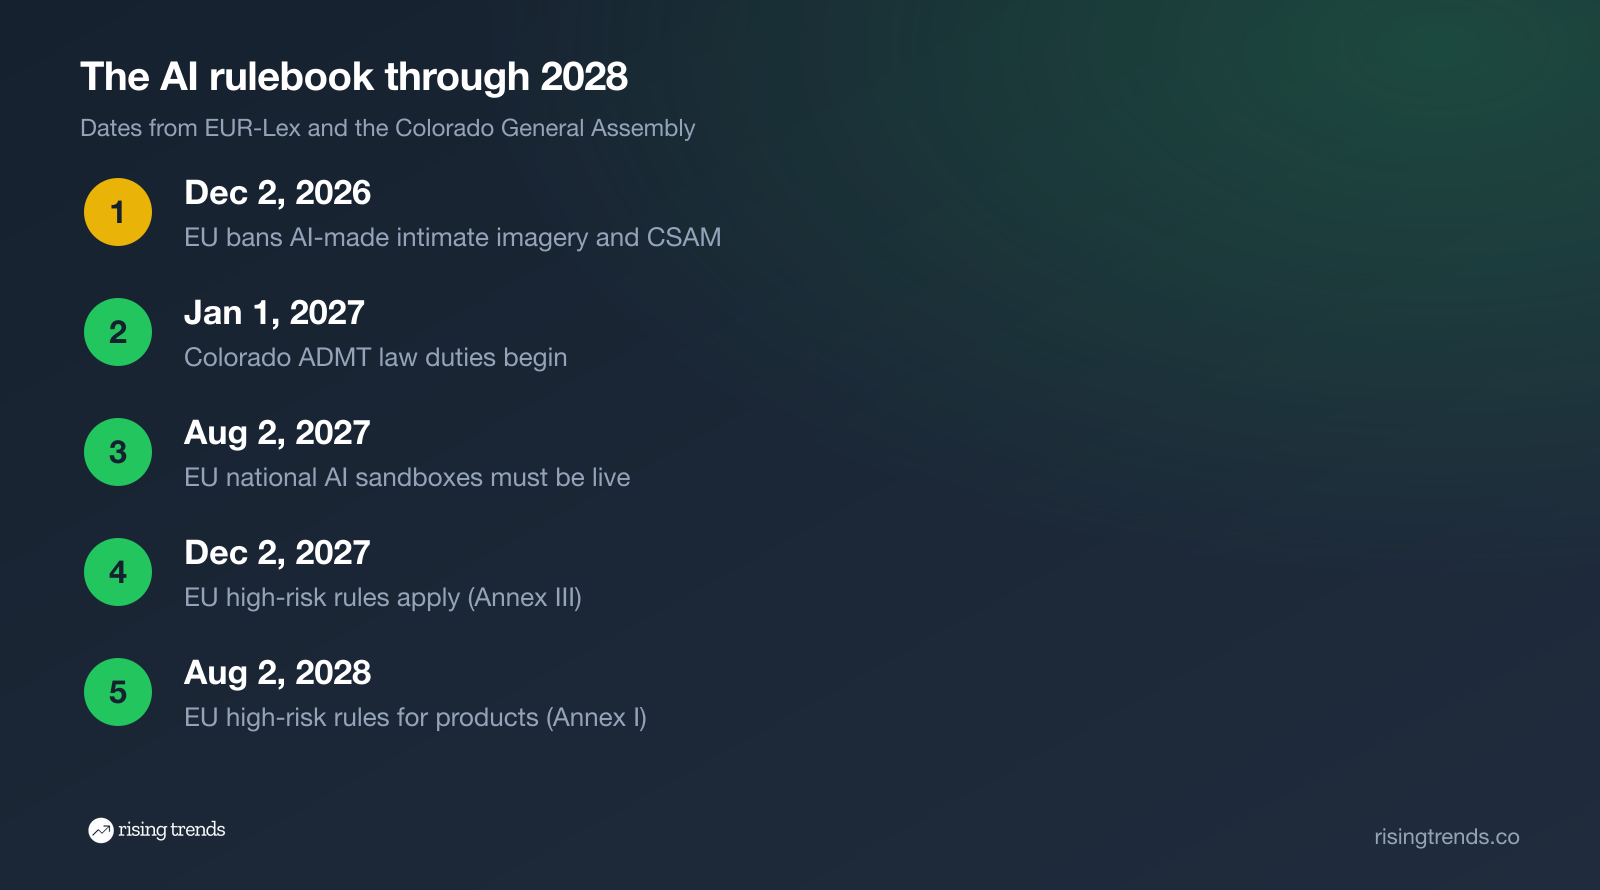
In the US, Colorado repealed and replaced its 2024 AI Act with SB26-189, a narrower automated decision-making law signed on May 14, 2026. Developer documentation duties begin January 1, 2027, with no private right of action. California's SB 53 frontier AI transparency law requires large frontier developers to publish safety frameworks and report critical incidents.
At the federal level, a December 2025 executive order created a Justice Department AI Litigation Task Force to challenge state AI laws and called for a national framework that preempts them.
For companies selling into Europe, the delay is breathing room, not a reprieve: December 2027 is now the date to plan HR, lending and education AI controls around. In the US, expect the fight between federal preemption and state laws to stay unsettled through 2027, which means building compliance for the strictest state you operate in.
The capability gap between the top models has nearly closed.
The 2026 AI Index found the top US model leads the best Chinese model by just 2.7% as of March 2026, and the best closed model leads the best open-weight model by about 3.3%. On the Arena leaderboard, four companies sit within 25 Elo points. The AI Index's own conclusion: competitive pressure is shifting toward cost, reliability and domain-specific performance.
DeepSeek released V4 with open weights: a 1.6 trillion parameter Pro model and a 284 billion parameter Flash model, both with a 1 million token context window. Google says its open Gemma models passed 900 million downloads. Amazon added more than 10 models to Bedrock in one quarter, including models from OpenAI, Anthropic, Google and xAI.
When the top models are within a few percent, the buying decision is about price per task, uptime, data residency and lock-in. Open-weight and Chinese models give a credible low-cost option, with sovereignty and compliance trade-offs that legal teams will need to sign off on. Our search data shows the interest: "chinese ai model" is up 400% in a year and "local ai models" up 303%.
AI coding tools are changing what companies buy.
McKinsey found 32% of organizations decided against buying at least one software product or feature in the past year because they could build it in-house with agentic coding tools. Among high performers it was nearly half. The AI Index reports SWE-bench Verified scores rising from 60% to near 100% in a year.
Vendors are repackaging in response. Salesforce re-segmented its revenue into "Agentforce Apps" and a "Headless Platform," selling its data and APIs to agents rather than only seats to people.
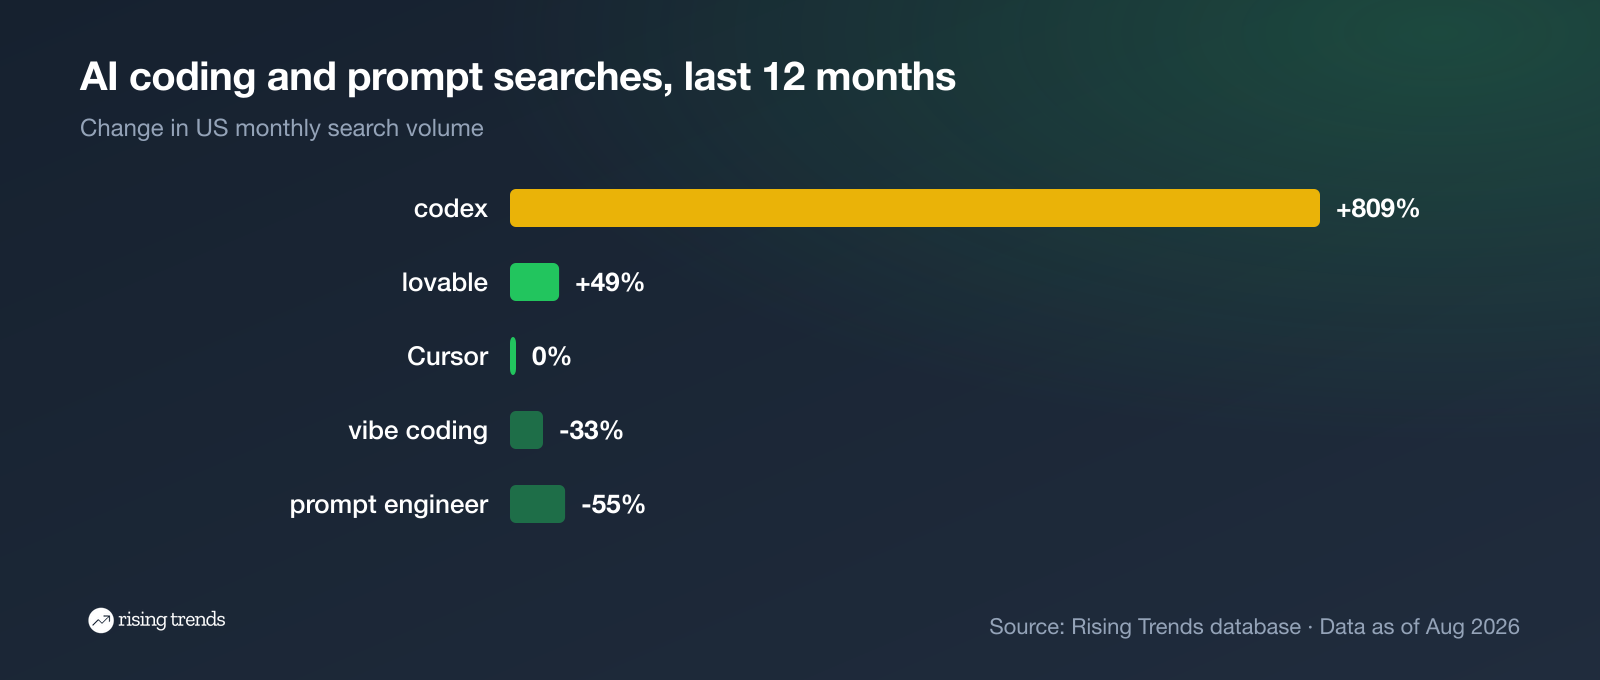
Our search data shows where developer attention went. "Codex" searches are up 809% in a year, to 550,000 a month, and "lovable" up 49%. "Vibe coding" is down 33% and "prompt engineer" down 55%: the novelty terms are fading as the tools become normal work. For more on how this changes engineering teams, see our software development trends.
Wholesale replacement of enterprise software is unlikely soon, but the threat is enough to change negotiations. Expect seat-based SaaS renewals to get harder in 2027, more internal tools built instead of bought, and software vendors pushing usage-based and agent-based pricing to protect revenue.
The labor impact of AI is showing up in hiring pipelines, not mass layoffs.
Stanford's Digital Economy Lab, using ADP payroll data through June 2026, found that employment for workers aged 22 to 25 in AI-exposed occupations is 19% below where it would be had it kept pace with less-exposed peers. That gap has widened with each update, from 13% in August 2025 to 16% in November 2025. The AI Index reports employment for software developers aged 22 to 25 fell nearly 20% from 2024.
Expectations run ahead of reality. In the McKinsey survey, 39% expect AI to reduce headcount next year, but only 14% saw an AI-driven workforce decline in the past year, less than half the 32% who had expected one.
The near-term risk for employers is not replacing staff but hollowing out the junior pipeline that produces future senior staff. Expect workforce plans in 2027 to separate "AI changes the role" from "AI removes the role," and expect scrutiny of entry-level hiring cuts, especially under the EU's employment-related high-risk rules from December 2027.
Our database tracks US search demand across tens of thousands of trends. For AI, as of August 2026, five patterns line up with the industry data above:
For the consumer side of AI, see our live AI trends table.
Put the ten shifts side by side and the pattern is clear: 2027 is the year AI has to pay for itself.
The infrastructure is already bought: hundreds of billions in leases and commitments start in 2027 whether demand shows up or not. The models are good enough and close enough that capability is no longer the bottleneck. What is scarce is power, memory and, above all, proof that AI moves the P&L. 37% of companies see any EBIT impact, and that number did not move in a year of record spending.
That puts the burden on the people buying AI, not just building it. If you plan for three things in 2027, plan for these: tie every AI program to a measurable outcome and redesign the workflow around it, because that is what the 6% of high performers do; build cost control into model choice, routing cheap work to cheap models before premium prices rise; and set your compliance calendar to December 2, 2027 in the EU and January 1, 2027 in Colorado.
The biggest shifts are the capex supercycle (with 2027 spending already locked in through leases), power becoming the main constraint, broad adoption with flat profit impact, AI agents moving into production, revenue concentrating in a few labs and clouds, a split in token prices, new EU and US state rules taking effect in 2027, converging model quality, coding agents changing build-vs-buy decisions, and pressure on entry-level jobs.
Amazon spent $173.0 billion on capex over the 12 months to June 2026, Microsoft $115.9 billion in fiscal 2026, and Meta guides $130 to $145 billion for 2026. The IEA says big tech capex exceeded $400 billion in 2025 and is expected to rise about 75% in 2026.
After the 2026 Digital Omnibus amendment, high-risk obligations apply from December 2, 2027 for Annex III systems such as AI used in hiring, education and credit, and from August 2, 2028 for AI embedded in regulated products.
For most, not yet at the P&L level. McKinsey's 2026 survey found 37% of organizations attribute any EBIT impact to AI, unchanged from 2025, and only about 6% get 5% or more of EBIT from it. Those high performers are far more likely to have redesigned workflows.
It is consolidating into the big platforms. OpenAI shut down the Sora app in April 2026 and the Sora API in September 2026, while Google says daily active video creators in the Gemini app grew 40% since May. Standalone consumer video generation proved hard to make pay.
Want to spot the next AI shift before it hits the mainstream? Read our guide on how to identify market trends or browse what's gaining traction in our trending topics list.
Join 5,000+ founders · Free